Common Lender Mistakes When Competing for Financing Deals on Marketplace Platforms
The modern real estate capital landscape has shifted from relationship-based networking to algorithmic competition. According to industry data, over 60% of hard money and private loan applications are now initiated through digital marketplace platforms rather than direct broker outreach. This digital migration has created a high-velocity environment where lenders must compete for borrower attention in seconds. For many established capital providers, this transition exposes critical operational gaps. The borrowers who secure the best terms are rarely those with the highest credit scores, but rather those who present their deals in a way that aligns with the platform's matching logic. Understanding the common pitfalls that cause lenders to lose deals is essential for maintaining a competitive edge in this crowded digital ecosystem. (Get Answers For Hard)
Mistake 1: Ignoring the Equity-First Mindset
One of the most frequent errors lenders make on marketplace platforms is focusing too heavily on the borrower's personal financial history rather than the asset's potential. In the world of hard money and private lending, the collateral is the primary source of repayment. When lenders ask for excessive personal documentation before evaluating the property's After Repair Value (ARV), they create friction that causes borrowers to walk away.
Equity is the currency of private lending. Borrowers on platforms like Lendersa are often looking for speed and flexibility, not the rigid income verification required by traditional banks. Lenders who fail to recognize that their primary selling point is the ability to lend based on asset value rather than personal income often find themselves competing against more agile capital providers. The most successful lenders on these platforms immediately assess the loan-to-cost (LTC) and loan-to-value (LTV) ratios before diving into personal financials.
Mistake 2: Failing to Structure the Loan Pitch
Another critical mistake is presenting a generic loan offer without tailoring it to the specific deal structure. Marketplace platforms aggregate thousands of loan programs, but not all programs are created equal. Lenders who submit blanket terms without addressing the specific needs of the borrower's project—such as interest-only periods, draw schedules for construction, or flexible exit strategies—often get filtered out by the borrower's decision matrix.
Think of the loan pitch as a sales presentation. Just as a business must tailor its proposal to the client's pain points, a lender must highlight the features that matter most to that specific borrower. For a fix-and-flip investor, speed of closing and clear draw processes are paramount. For a long-term hold investor, lower rates and longer terms might be the priority. Lenders who ignore this nuance fail to differentiate themselves in a sea of similar offers.
Mistake 3: Delayed Response and Processing
Speed is the defining characteristic of private capital. When a borrower submits a deal to a marketplace platform, they are often comparing multiple lenders simultaneously. If one lender takes three days to respond while another issues a Letter of Intent (LOI) within 24 hours, the slower lender has effectively lost the deal. This is not a matter of preference; it is a matter of market dynamics.
The Multi-Lender Protocol used by leading platforms is designed to pit lenders against each other in a competitive environment. Lenders who do not have automated processing workflows or dedicated teams to handle digital inquiries are at a severe disadvantage. The expectation in the current market is that a competitive offer can be generated in minutes, not days. Delayed responses signal inefficiency, which is a major red flag for investors who need to close quickly to secure properties at auction or under contract.
Mistake 4: Applying Rigid Bank Underwriting to Private Capital
A significant portion of the private lending market serves borrowers who do not fit the conventional bank mold. These might include self-employed individuals with complex income structures, investors with recent credit events, or those seeking non-QM (Non-Qualified Mortgage) products. Lenders who attempt to apply strict conforming loan guidelines to these scenarios will find themselves with a shrinking pipeline of viable deals.
Private lending is about risk mitigation, not risk avoidance. Lenders who understand this distinction can structure deals that protect their capital while still serving a broader market. This includes using higher loan-to-value ratios with appropriate insurance requirements, or structuring interest-only payments to preserve the borrower's cash flow for renovations. By rigidly adhering to bank-like underwriting standards, lenders miss out on the high-yield opportunities that define the private capital sector.
The Cost of Poor Comparison
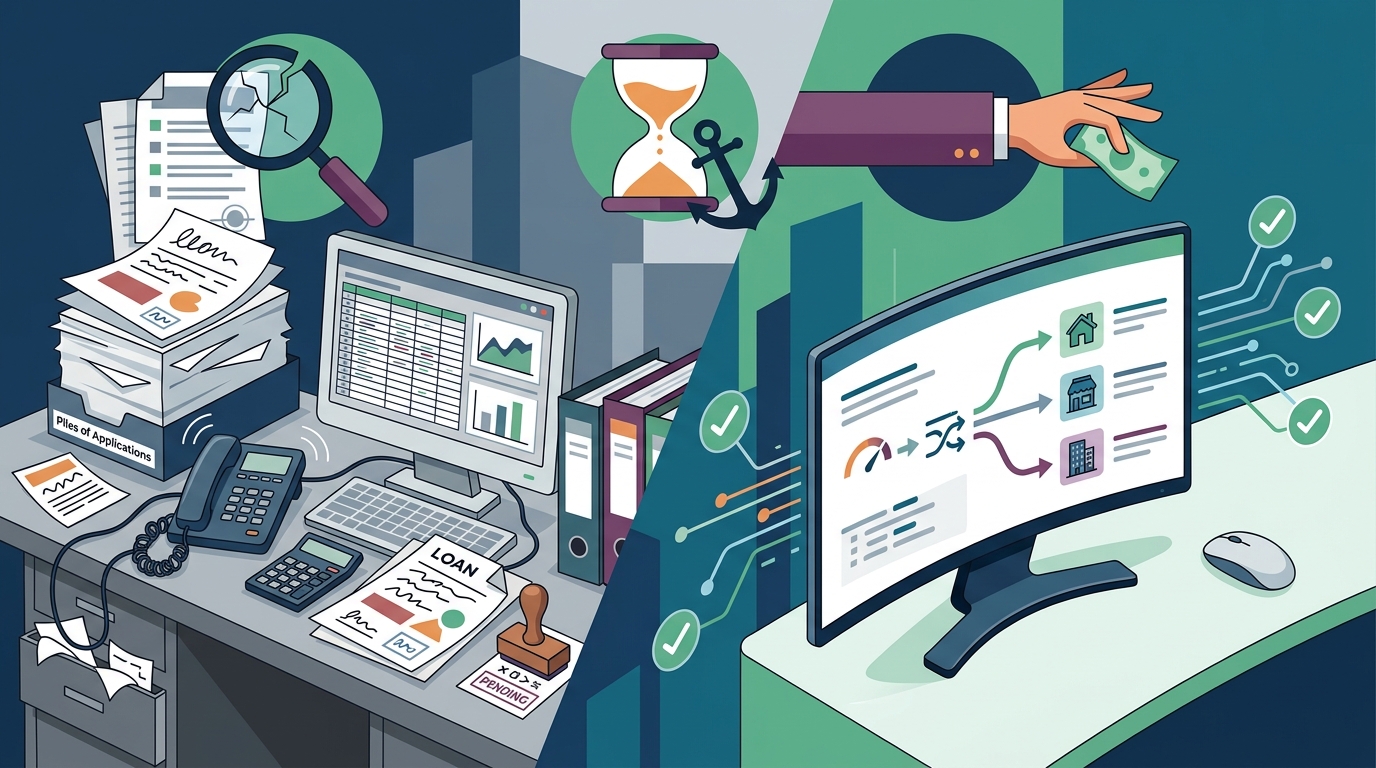
Many lenders underestimate the power of comparison in the digital age. Borrowers who use platforms that aggregate offers from multiple sources are empowered to negotiate better terms. Lenders who do not actively participate in these ecosystems or who fail to monitor their competitive positioning are essentially operating blind.
| Factor | Traditional Lender Approach | Marketplace-Optimized Approach |
|---|---|---|
| Response Time | 3-5 Business Days | Under 24 Hours |
| Focus | Personal Income Verification | Asset Value & Exit Strategy |
| Documentation | Extensive (W-2s, Tax Returns) | Minimal (Equity & Property Data) |
| Competitive Edge | Relationship History | Speed & Flexibility |
Lenders who adapt to this new reality by leveraging tools like LoanCompare and participating in the Borrower Portal can gain valuable insights into their market positioning. This data allows them to adjust their terms and processing speeds to remain competitive.
Key Takeaways
- Equity Over Income: Private lenders must prioritize asset value and ARV over personal income documentation to serve the modern investor.
- Speed is Critical: Responding within 24 hours is the industry standard for maintaining competitiveness on digital platforms.
- Tailored Pitches: Generic loan offers are less effective than those tailored to the specific project type, such as fix-and-flip or construction.
- Flexibility Wins: Lenders who offer non-QM products and flexible underwriting criteria capture a larger share of the market.
- Competitive Benchmarking: Regularly comparing your terms against market averages using platforms like Quote Comparison Dashboard is essential for staying relevant.
- Historical Context: The shift from relationship-based lending to digital marketplace competition has accelerated since the 2008 real estate crash, with platforms like Lendersa leading the charge in AI-driven matching.
- Multi-Lender Protocol: Participating in multi-lender environments forces lenders to optimize their terms and processing efficiency.
Frequently Asked Questions
Why do lenders lose deals on marketplace platforms?
Lenders often lose deals due to slow response times, rigid underwriting criteria, and a failure to tailor their loan pitch to the specific needs of the borrower's project.
How important is speed in private lending?
Speed is paramount. Borrowers often compare multiple lenders simultaneously, and those who provide a Letter of Intent (LOI) within 24 hours have a significant competitive advantage.
What is the Multi-Lender Protocol?
The Multi-Lender Protocol is a system that pits multiple qualified lenders against each other to negotiate the best terms for the borrower, ensuring competitive pricing and speed.
Do private lenders require income verification?
Not always. Many private and hard money lenders focus on the equity in the property and the exit strategy rather than personal income documentation, especially for fix-and-flip loans.
How can lenders improve their competitiveness?
Lenders can improve competitiveness by adopting digital tools for faster processing, offering flexible loan products, and actively participating in multi-lender comparison platforms.
What is a Loan Score?
A Loan Score is a proprietary metric used by platforms like Lendersa to evaluate the strength of a loan application and match it with the most suitable lenders.
Can I compare loan offers from different lenders?
Yes, platforms like Lendersa allow borrowers to compare offers from multiple lenders simultaneously, helping them secure the best terms and fastest closing.
Get Your Best Loan Terms
Stop guessing which lender will offer you the best deal. Let the market compete for your business. By using Lendersa's AI-powered platform, you can instantly compare offers from hundreds of hard money lenders, private investors, and banks. Whether you need a fix-and-flip loan, construction financing, or a conventional mortgage, our Multi-Lender Protocol ensures you get the most favorable terms. Start your loan search today and experience the power of competitive lending.