Online loan marketplaces are digital platforms that connect borrowers with multiple lenders simultaneously, allowing capital providers to bid on specific deal parameters. For lenders, these platforms shift the traditional outbound lead generation model to an inbound, data-driven competition where underwriting criteria dictate deal flow. By integrating directly into these ecosystems, lenders can access high-intent files that match their exact risk profiles, reducing wasted underwriting hours on unqualified requests.
The Shift from Cold Outreach to Data-Driven Deal Flow
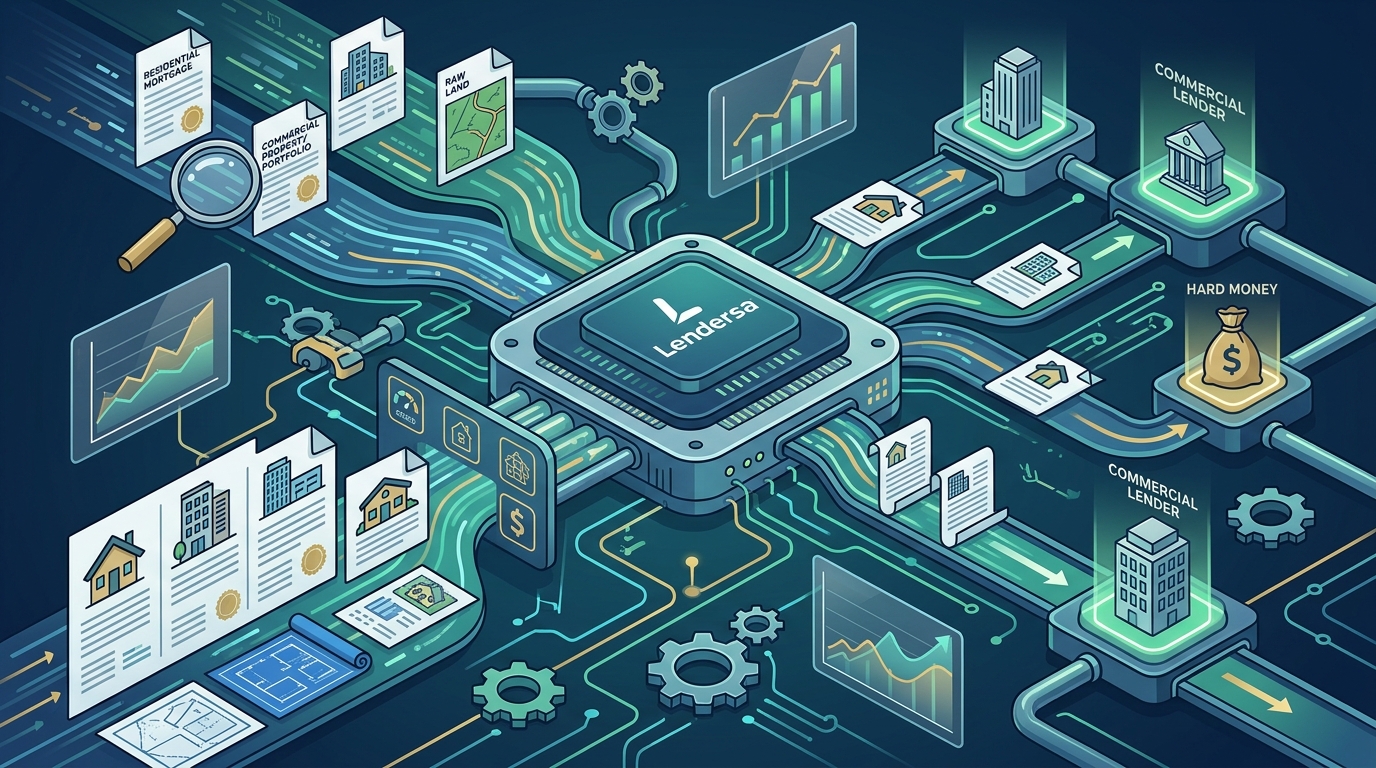
Traditional lead generation often relies on broad marketing campaigns that result in low-intent inquiries. In contrast, an online loan marketplace operates on a strict matching protocol. When a borrower submits a request, the platform analyzes the asset's metrics, such as loan-to-value and property type, before distributing the file. This ensures that a lender only receives a lead if it fits their pre-defined underwriting sandbox. For example, a direct lender focused on commercial bridge loans in California can configure their profile to receive only files with a loan amount above $500,000 and a specific credit score threshold.
Understanding the Multi-Lender Protocol
The core mechanism of a modern lending platform is the multi-lender protocol. This system allows a single borrower's request to be broadcast to multiple qualified lenders at once. Instead of a borrower calling five different banks, the platform's algorithm identifies the lenders whose guidelines align with the borrower's scenario. This creates a competitive environment where lenders must offer their best terms to win the deal. The implication for lenders is that they must maintain competitive pricing and fast turnaround times, as the borrower can see multiple offers side-by-side in a secure dashboard.
Privacy and the Asset-Based Firewall
One of the most significant advantages of using a structured marketplace is the protection of borrower data. Many platforms utilize a data firewall that keeps the borrower's identity hidden until a lender submits a binding offer. This means lenders can evaluate the strength of the asset, such as the property's equity and cash flow, without triggering a hard credit inquiry or exposing the borrower's personal information. This approach builds trust and ensures that lenders are competing on the merit of the deal rather than through aggressive sales tactics. It also protects the lender from the risk of their data being shared with unauthorized third parties.
Optimizing Your Lender Profile for Visibility
To succeed in a marketplace, a lender's digital presence must be highly optimized. This includes maintaining up-to-date underwriting guidelines and a clear profile that highlights specific strengths, such as fast funding times or flexible terms. Lenders can use platform-specific tools to adjust their criteria in real-time based on market conditions. For instance, if a lender wants to focus on fix-and-flip projects in a specific state, they can narrow their lead capture settings to reflect that niche. This precision ensures that the deal flow is relevant and actionable, allowing the lender's team to focus on closing rather than filtering out junk leads.
The Economics of Pay-on-Success Models
Many online loan marketplaces operate on a pay-on-success or no-closing-no-fee model. This means that lenders do not pay a subscription fee to access the platform or to view leads. Instead, they only pay a small marketing fee when a loan successfully closes. This model aligns the interests of the platform and the lender, as both parties benefit from a successful transaction. For lenders, this reduces the financial risk of lead generation and ensures that their marketing budget is directly tied to actual revenue. It is a more efficient use of capital compared to traditional advertising, where costs are incurred regardless of the outcome.
Key Takeaways
- Online loan marketplaces use data-driven matching to ensure lenders only receive leads that fit their specific underwriting criteria.
- The multi-lender protocol creates a competitive bidding environment where lenders must offer competitive terms to win deals.
- Data firewalls protect borrower privacy by keeping identities hidden until a lender submits a binding offer.
- Optimizing your lender profile with precise underwriting guidelines improves the quality and relevance of the deal flow you receive.
- Pay-on-success models reduce financial risk by only charging lenders when a loan successfully closes.
- Using a marketplace allows lenders to scale their origination efforts without the high costs of traditional lead generation.
Frequently Asked Questions
What is an online loan marketplace?
An online loan marketplace is a digital platform that connects borrowers with multiple lenders, allowing them to compare offers and enabling lenders to bid on deals that match their criteria.
How do lenders get leads on these platforms?
Lenders receive leads when a borrower's request matches the lender's pre-defined underwriting guidelines, such as loan amount, property type, and location.
Is my borrower data safe on a loan marketplace?
Yes, most reputable platforms use data firewalls to keep borrower identities hidden until a lender submits a binding offer, protecting both parties' privacy.
Do I have to pay to use a loan marketplace?
Many platforms operate on a pay-on-success model, meaning you only pay a fee when a loan successfully closes, with no upfront subscription costs.
Can I customize which leads I receive?
Yes, lenders can configure their profiles to specify exact criteria for the deals they want to see, ensuring they only receive relevant and actionable files.
How does a marketplace benefit a direct lender?
A marketplace provides direct lenders with a steady stream of high-intent, pre-qualified leads, reducing the time and cost associated with traditional outbound marketing.
Start Competing for Better Deals
To begin accessing high-quality deal flow, lenders can register on the Lendersa Capital Portal. This platform allows you to define your exact underwriting criteria and start receiving leads that fit your business model. By joining a data-driven marketplace, you can scale your origination efforts and compete for the best deals in your market.