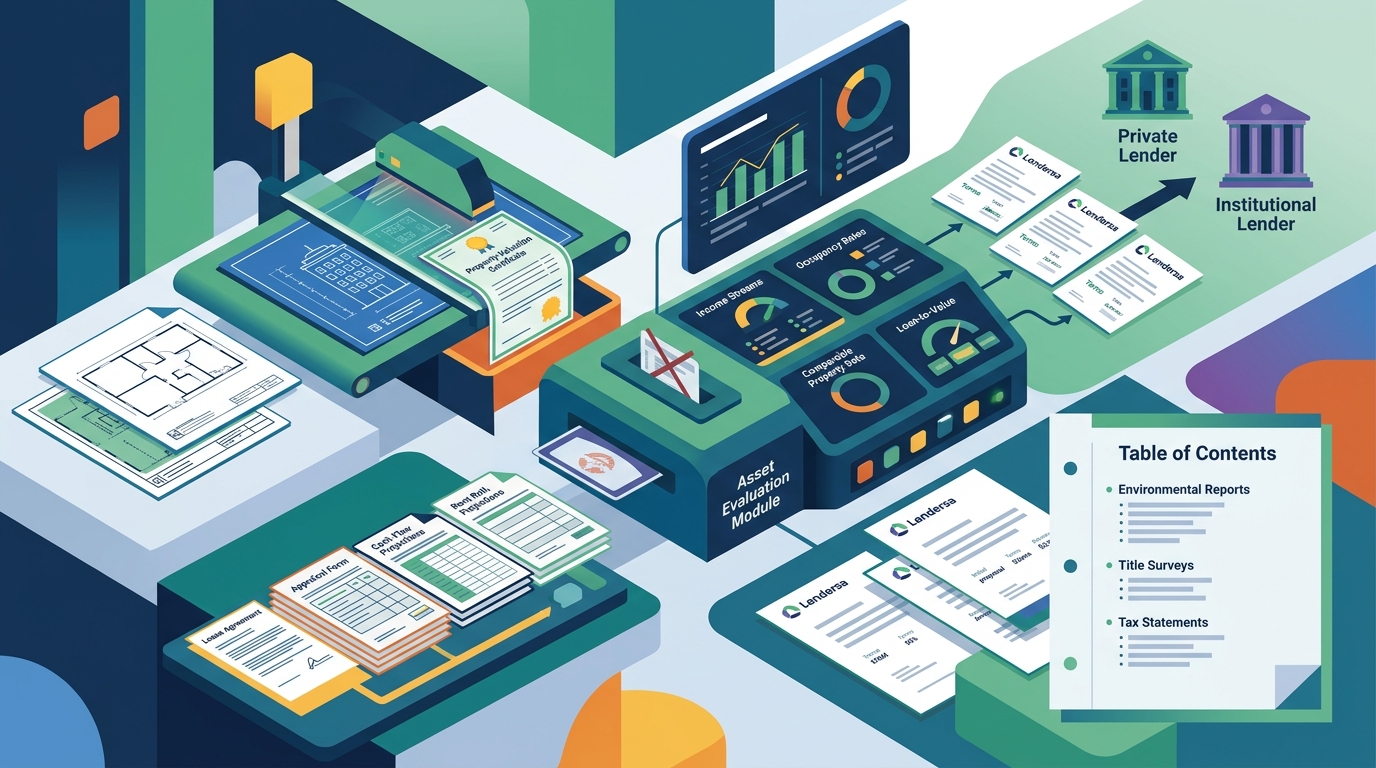
Commercial property owners can secure financing by providing asset-based documents that prove property value and cash flow, bypassing the need for a Social Security Number. Lendersa enables this by using an asset-based matching protocol that evaluates the collateral rather than personal identity. This approach allows investors to receive initial loan proposals based on the strength of the real estate itself, ensuring privacy while accessing competitive capital from private and institutional lenders.
The Asset-Based Underwriting Model
Traditional bank underwriting relies heavily on personal credit history and income verification, which requires an SSN. In contrast, private and hard money lending focuses on the asset. A hard money loan is a type of loan that is secured by real property, meaning the collateral dictates the terms rather than the borrower's personal financial profile. When you submit a request to Lendersa, the system analyzes the property's equity and cash flow metrics. This model is particularly effective for commercial properties where the entity may not have a long credit history. By focusing on the asset, lenders can make informed decisions without accessing sensitive personal identifiers.
Essential Property Valuation Documents
To establish the value of your commercial property, you must provide documentation that supports the Loan-to-Value (LTV) ratio. The LTV is the ratio between the loan amount and the property value, which is the most critical factor in approving a hard money loan. You should include a recent appraisal or a Comparative Market Analysis (CMA) to justify the property's worth. Additionally, providing a title commitment or a preliminary title report helps verify ownership and any existing liens. These documents allow the lender to assess the safety margin of the investment. For example, if a property is valued at $1,000,000 and you request a $600,000 loan, your LTV is 60%, which is generally considered a safe threshold for most private lenders.
Proof of Income and Cash Flow
While personal income verification is often skipped, commercial lenders still need to see that the property generates sufficient revenue. You should provide the last two to three years of tax returns for the property or the operating entity. If the property is new or recently acquired, a pro forma income statement can be used to project future cash flows. These documents demonstrate the property's ability to service the debt. Lendersa's AI tools can help you structure this data into a clear format that lenders can quickly review. By presenting a strong cash flow story, you increase your chances of receiving a favorable interest rate and lower fees.
Entity and Ownership Documentation
Commercial real estate loans are often made to business entities such as corporations, limited partnerships, or trusts. You need to provide the entity's formation documents, such as Articles of Incorporation or a Certificate of Formation. Additionally, a list of the entity's principals or owners is required to identify who has authority to sign the loan documents. If the entity does not have a credit history, lenders may require a personal guarantee from the principals. However, the initial matching process on Lendersa does not require your SSN, allowing you to gauge interest before committing to a personal guarantee. This step ensures that you are only sharing sensitive information with lenders who have already shown a strong interest in your deal.
Using Lendersa for Privacy and Competition
Lendersa operates on a Multi-Lender Protocol that protects your data through a proprietary Data Firewall. This system creates isolated, encrypted environments for each bidding lender, ensuring that your identity remains hidden until you choose to release it. You can upload your property documents and receive binding offers from multiple lenders without exposing your SSN or personal contact information. This competitive environment forces lenders to bid on the strength of your asset, often resulting in better terms. By using Lendersa, you maintain control over your data while accessing a wide network of private and institutional capital.
Key Takeaways
- Asset-based underwriting focuses on property value and cash flow, not personal credit.
- Provide a recent appraisal or CMA to establish the property's value and LTV.
- Include tax returns or pro forma statements to prove the property's income potential.
- Submit entity formation documents to verify ownership and authority.
- Lendersa's Data Firewall keeps your SSN and identity private during the initial bidding phase.
- Competitive bidding from multiple lenders can lead to better rates and lower fees.
Frequently Asked Questions
Do I need to provide my SSN to get a loan quote on Lendersa?
No, Lendersa uses an asset-based matching protocol that does not require an SSN for initial matching. Your data remains anonymized until you choose to release it to a specific lender.
What is the most important document for a commercial hard money loan?
The most important document is the property appraisal or valuation report, as it determines the Loan-to-Value (LTV) ratio, which is the primary factor in loan approval.
Can I get a loan if my entity has no credit history?
Yes, private lenders focus on the asset's value and cash flow. If the entity has no credit history, lenders may require a personal guarantee from the principals, but the initial quote can be obtained without it.
How long does it take to receive loan offers on Lendersa?
Lendersa's AI matches your loan scenario against thousands of active lenders in minutes, allowing you to receive initial proposals quickly.
What types of commercial properties are eligible for financing?
Lendersa supports financing for various commercial property types, including retail, office, industrial, and multifamily properties, as well as vacant land.